
Futsal betting tips 2026: reading prices, building a bankroll and accepting the margin
 Available in US
Data current as of October 30, 2026 · verified against the Gambling Commission’s public register of remote operating licences.
Anyone searching for futsal betting tips is, in practice, searching for someone to tell them what is going to happen. That is not what this page is. The page below treats a “tip” as a price the punter has decided is bigger than the chance of the thing occurring — a value bet, in the trade’s own word — and walks through every step the reader has to take to reach one without inventing what they cannot know. The conclusion this page reaches is unflattering: no published tip beats the bookmaker’s take long-term, and the only sustainable edge a reader can build is discipline applied to prices that already exist. The rest of this guide is the work of reaching that conclusion in plain language.
Futsal is a small-sided indoor game, two twenty-minute periods with the clock stopping at dead-ball situations, played by two teams of five with up to nine substitutes and unlimited changes — a tempo of substitutions that opens the betting market wider than the same reader expects from outdoor football. The court is forty metres by twenty, the ball is size four, heavier than a size five and with a lower bounce. From the sixth accumulated foul in a period the opposition gets a direct free kick from ten metres with no wall, a rule bookmakers price into the totals goal line. That the sport is shorter, faster and structurally different from eleven-a-side is exactly why a tip that worked on football will not transfer cleanly.
What the rulebook says about a futsal betting tip
A “tip” in the betting trade is shorthand for a price on an outcome that the tipster believes is wrong in their favour. The mechanism has not changed since the first price was printed in a newspaper: a bookmaker offers odds on outcomes, the punter stakes against them, the bookmaker takes a margin out of every market, and the difference between the punter’s view and the book’s view is what the punter is trying to capture.
The reason no tip is ever certain is mathematical, not motivational. A bookmaker’s margin sits inside every price — £1 staked at decimal odds 2.00 returns £2 only if the outcome is true, and the £1 of profit is the punter’s reward for a probability the bookmaker has already priced below 100 %. Take the margin out, set the implied probabilities, and the punter is asking the bookmaker to have got one of them wrong. Sometimes the bookmaker is wrong. Over hundreds of bets, the margin collects its share from both winners and losers. The punter’s job is to find the prices where the bookmaker is wrong more often than the margin collects.
A value bet, then, is a price that the punter’s own probability estimate exceeds, after the margin has been taken out. The estimate has to come from somewhere — form, head-to-head, line-ups, the run of play, the squad rotation pattern of a club playing twice in three days. The punter who builds an estimate from futsal-specific data and only bets when the price exceeds that estimate is doing what a tipster does in principle, and is doing it without paying a subscription to someone who calls one lucky line a “system”. The number of bets that survive this test is small. That is the point.
The bookmaker’s margin is the second thing every tip has to be measured against, and it is the one thing the trade has agreed to call a word “overround”. A two-way market priced 1.90 / 1.90 is not a fair 50/50 — the payout share is 1 ÷ (1/1.90 + 1/1.90) = 0.526, which means the margin is roughly 47.4 % before either side is settled. A reader who saw 1.90 / 1.90 and read “50/50” has misread the page. The implied probability of each side is 52.6 %, not 50 %, and the 2.6 points of overround on each side are the book’s take. A market priced 1.95 / 1.95 carries a smaller margin (a payout share of 0.513 each side, about 48.7 % overround in total), and a market priced 1.85 / 1.85 carries a bigger one (0.541 each side, about 54.1 % overround). The shape of the spread is the shape of what the bookmaker is keeping.
The way a punter sees the margin in the odds is to add the implied probabilities. Two 1.90 prices sum to 105.3 % — the extra 5.3 % is the margin. The closer that sum is to 100 %, the fairer the market. A two-way price where the sum runs to 105 % is ordinary; a sum at 108 % is a market the bookmaker is being paid more on; a sum at 102 % is a price of market a sharper punter will look harder at. The reader who learned only one thing from this page — add the implied probabilities before staking — has learned the most useful thing it carries.
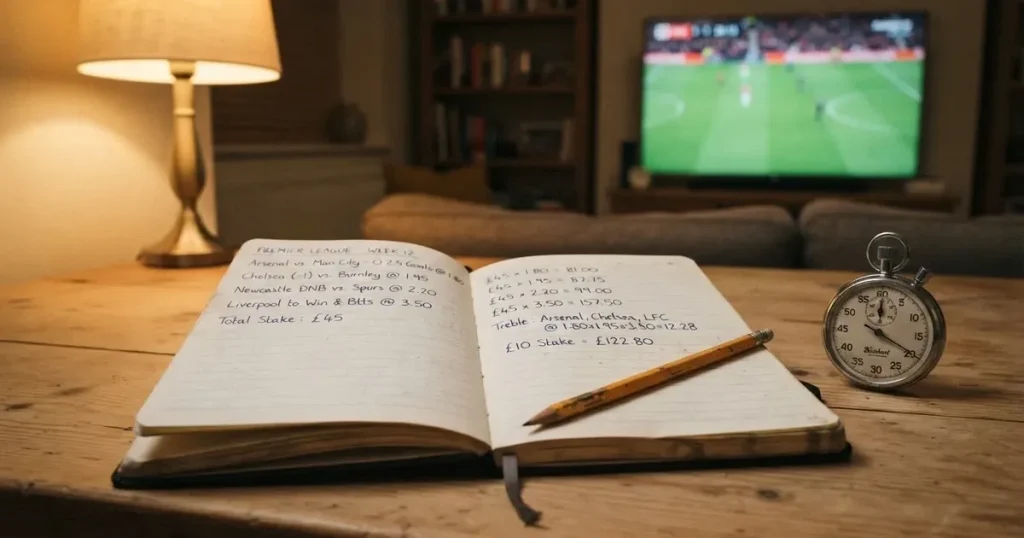
The return on a bet, given a stake and decimal odds, is the stake multiplied by the odds. A £10 stake at 2.50 returns £25 — £10 of stake returned, £15 of profit. A £10 stake at 1.50 returns £15 — £10 of stake, £5 of profit. For an accumulator the odds of the legs multiply into one price, and the same arithmetic applies to the multiplied price: a four-fold of legs at 2.00, 1.80, 1.95 and 2.10 produces combined odds of 14.65, and a £10 stake returns £146.50 if all four land. The arithmetic does not care about the order of the legs or the order of the matches; it is mechanical, and a punter who knows the multiplication has taken the mechanical surprise out of an accumulator.
How the law treats a futsal bettor in Great Britain
Futsal betting in Great Britain is regulated by the Gambling Commission, a non-departmental public body sponsored by the Department for Culture, Media and Sport, under the Gambling Act 2005. The Act covers England, Scotland and Wales; Northern Ireland has its own older law and is outside the 2005 Act, so a “GB licence” never means a Northern Irish one. Since the Gambling (Licensing and Advertising) Act 2014 an operator whose remote facilities are used in Great Britain needs a Commission licence wherever it is based — sections 33 and 36 of the 2005 Act as amended — and a Curaçao, Maltese or Gibraltar licence is not a substitute. There is no state monopoly and no cap on how many licences the Commission can issue.
The licence categories a futsal punter will see in the Commission’s public register are remote general betting standard (real events), which is what covers a fixed-odds bookmaker offering a futsal match, and remote betting intermediary, which covers a betting exchange. Spread betting on a financial product is regulated by the Financial Conduct Authority, not the Commission, and a spread-betting firm’s losses can exceed the deposit. The Commission’s register is searchable by business name, trading name, domain or account number, and is the whole test of whether a brand holds a licence — a domain proves nothing, because licensed operators use both .com and .co.uk. The page’s own featured operators are all on that register, and each is named with the account number the register gives. A punter who is unsure whether a brand is licensed should check the register before staking, not after.
The minimum age for a bet placed with a licensed operator is 18. Since 7 May 2019 every licensed remote operator has to verify name, address and date of birth before a customer can deposit or gamble, including with a free bet or bonus — anonymous play is no longer available at a licensed site. The verification is not optional at the punter’s discretion: it is a licence condition, and the punter who objects to it is choosing between licensed and unlicensed, with the loss of protections that choice carries.
There is no statutory list of permitted bets or markets in the Gambling Act 2005. A licensed operator holds a category of licence and offers markets under its own rules and the Licence Conditions and Codes of Practice (LCCP). In-play on a licensed site is permitted; the controls are the operator’s licence conditions and customer-protection duties, not a statutory restriction. Esports, virtual events, politics and novelty markets are all offered by GB bookmakers, with no statutory prohibition. There is no state-set cap on stakes in sports betting: operators set their own maximum stakes and may restrict individual customers. The reader who looks to the statute for a list of “what is legal” is looking for a document that does not exist — the rule is the licence, the rules are the operator’s terms.
What the statute does set, firmly, is the frame around the bet: the player protection regime, the payments regime, the advertising regime and the tax frame. The next three sections of this page go through each in turn, because every bookmaker on the featured list operates inside this frame whether the brand talks about it in its marketing or not.
What a licensed bookmaker must offer a futsal punter
A GB-licensed online operator is part of GAMSTOP, the national multi-operator online self-exclusion scheme and a mandatory licence condition since 31 March 2020. Self-exclusion can be set for six months, one year, five years, or five years with auto-renewal; after the minimum period the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps; betting shops run a separate self-exclusion service. The punter who has registered with GAMSTOP cannot deposit or bet with a GB-licensed operator until the period ends. There is no charge to register.
A financial vulnerability check applies to licensed remote betting when a customer’s deposits minus withdrawals exceed £150 in a rolling 30 days. The check, in force since 28 February 2025, is a public-record check (bankruptcy or county court judgments), not an income check and not a credit reference check. Financial risk assessments — the “affordability checks” of the press — were announced by the Commission on 7 July 2026 in a staged plan, with no start date; the page writes the present position as “announced, staged, no start date”, not “in force”. Deposit limits on licensed sites are an RTS 12 requirement: operators must offer a gross deposit limit on a fixed time frame, with a first phase live since 31 October 2025 and a second phase postponed to 30 September 2026, and whether it is live is not established. There is no state-set deposit or loss ceiling for betting: limits are the customer’s choice. The punter who wants a £5 weekly ceiling can set one; the punter who wants a £500 daily ceiling can set that instead.
Credit cards are banned for gambling in Great Britain since 14 April 2020 (LCCP condition 6.1.2), and the ban covers credit-card-funded payments through an e-wallet. Debit cards and bank-based payments are not caught. The punter who tries to deposit on credit at a licensed site is refused at the cashier, and the bookmaker’s payment screen is the first place the rule shows up. The punter who wants to deposit by crypto should expect no licensed GB bookmaker to offer it as a standard option; whether any individual operator accepts it is for the operator’s own terms.
Advertising is not licensed by the Commission. It runs through the CAP Code (non-broadcast) and BCAP Code (broadcast), enforced by the ASA, alongside the LCCP marketing conditions. CAP Code section 16: marketing must be socially responsible, must not be of strong appeal to under-18s, and no one who is or seems to be under 25 may be featured gambling or play a significant role in a gambling ad, with an exception for marketing placed where a bet can be made directly. That rule is about who may appear in an ad, not who may bet. Promotion rules in force since 19 January 2026 cap wagering requirements on bonuses at 10x — a £10 bonus at 50x wagering, the kind that used to ship as a headline, requires £500 of bets under the old regime and is now barred at a licensed site — and mixed-product promotions, an offer that requires gambling on two or more product types such as “bet on football to get free spins”, are banned. Whether the 10x cap applies to free bets with no wagering condition, and any cap on the money value of a bonus, are not established. The punter who sees a headline that looks too generous should read the small print for the wagering figure.
Help is available regardless of which licensed operator a punter uses. GamCare runs the National Gambling Helpline; GambleAware funds treatment and education; the NHS runs gambling clinics in several cities; Gamblers Anonymous runs meetings. A punter who feels the betting is running ahead of them can register with GAMSTOP, can set a deposit limit, can ask the operator for a product restriction, or can self-exclude through the operator without using GAMSTOP at all. None of these is a punishment. They are the licence conditions the bookmaker has signed up to.
Bonuses, free bets and the cost of “free” on a futsl bet
A bonus at a GB-licensed bookmaker is governed by the same 10x wagering cap as any other promotion since 19 January 2026: no more than ten times the bonus amount in qualifying bets. The trade’s word “free bet” describes a token whose stake is not returned with a win — a £10 free bet at decimal odds 2.50 returns £25 if it wins, the same as a £10 stake at 2.50, except the original £10 is not paid back, which makes the net profit £15, not £25. The trade’s word “risk-free” usually describes a free-bet refund on a losing stake, not a cash refund, and the punter who treats “risk-free” as a synonym for “no risk” is reading the marketing word and not the terms.
The arithmetic of what a frees up is worth on a winning bet starts from the price. A free bet at decimal odds 2.00 produces a £10 net profit on a win, which is half the net profit of a £10 stake at the same price. The odds 3.00 doubles the net profit to £20. The price multiplies the value. The free bet the punter is most tempted to use — the one at long odds, because long odds look like a big payout — is the one with the most value, because the stake’s absence hurts less when the multiplier is large. The punter who uses a free bet at 1.20 is leaving most of its value on the table.
A welcome offer that pairs a sportsbook bonus with a casino bonus, the kind that ships as “bet on football to get free spins”, is a mixed-product promotion and is banned at a licensed site since 19 January 2026. A welcome offer that ships only as a sportsbook free bet with a 10x wagering cap is the form a licensed welcome offer now takes. The punter who reads “50 % back as a free bet of up to £50” knows the maximum nominal value of the offer, knows the stake is not returned on a win, and knows the wagering cap governs how the bonus is cleared. The trade’s “100 % bonus” — the word the marketing prefers — is a match on the deposit, capped at the operator’s stated maximum, and the wagering cap means a £100 bonus still requires £1,000 of qualifying bets at 10x.
The cost of a bonus is the turnover multiplied by the market’s margin. A £100 bonus at 10x is £1,000 of qualifying bets. If the punter clears the bonus on a market with a 5 % margin, the expected cost of clearing is £1,000 × 0.05 = £50 — half the nominal value of the bonus. A punter who clears on a market with a 10 % margin loses £100 of expected value on a £100 bonus, which means the bonus has cleared the punter rather than the other way around. The margin of the bet that beats the wagering requirement matters more than the headline value of the bonus.
The qualifying-bet rule, the minimum odds rule and the time limit on a bonus are the conditions that turn a generous headline into an ordinary one. The punter who reads the bonus terms before staking will see the minimum odds (usually 1.50 or 2.00), the list of markets that do and do not qualify (often cash-out bets and system bets are excluded), the wagering multiple (now capped at 10x), and the deadline (often seven or fourteen days). The deadline is the trap most often missed: a punter who clears half the turnover before the deadline forfeits the rest, and the bonus terms say so. The punter who treats a bonus as a coupon that takes a weekend to clear is the punter the bonus is written against.
A bookmaker’s headline price boost, the trade’s “enhanced odds” or “price boost”, is a one-off promotion on a named outcome. The boost is genuine: the boosted price is genuinely bigger than the static price. The boost is also a marketing device: the punter who stakes on the boosted outcome carries the same margin that the static price carries, plus whatever extra margin the boost has applied to lure the stake. The boost is worth what the boosted price is worth on its own, which is the static probability of the outcome multiplied by the boosted price minus one. A punter who treats a price boost as a free upgrade is reading the marketing word and not the terms.
The futsal-specific market a bonus can be cleared on is narrower than the football market. Futsal is a smaller sport, fewer events are live at any one moment, and the bookmakers who price it seriously are a smaller subset than the bookmakers who price the Premier League. A bonus that can only be cleared on football markets is, for a futsal punter, a bonus that takes the football market’s margin on its turnover. The punter who reads “sports bonus” as “futssal-friendly” is over-reading the marketing.
Live betting, in-play prices and the cost of cashing out early
In-play on futsal is offered by every bookmaker on the featured list, and the in-play product is a separate pricing engine to the pre-match one. The price on a live game moves with the score, the time and the pattern of play; the price moves faster than a punter can re-enter a search box, and the punter who waits for a price to look “obviously wrong” is reading a price the bookmaker has already moved. The market’s word for that is “suspension” — the bookmaker takes the market down during a goal, a red card or a timeout, and re-opens it at a new set of prices a few seconds later. The punter who sees a suspended market has not seen an error; they have seen the trade at work.
The live market on a futsal match is structurally smaller than the live market on a football match, which means the margin is wider and the prices are less efficient. A futsal live market on a smaller league, where the bookmaker has fewer liquidity sources, can carry a 10 % margin where a Premier League live market carries a 3 % margin. The punter who treats a futsal live price as if it were a football live price is comparing two different books.
Cash out is the bookmaker’s offer to settle a bet early, at a price the bookmaker sets. The price the bookmaker offers is not the live price of the same selection: it is the bookmaker’s own price for buying the bet back, which carries its own margin. The cash-out price on a winning bet is lower than the price the punter would receive by waiting for the final whistle; the cash-out price on a losing bet is higher than the price the punter would receive by letting the bet ride. The bookmaker is paying a small premium on the losing side and charging a small premium on the winning side. The punter who reads cash-out as “free money” is reading the marketing word.
The price boost in-play is a one-off increase on a named live selection. The cost of the boost is the same as the cost of a pre-match boost: the boosted price is genuinely bigger, and the margin is still inside the price. The punter who reads a boosted live price as a fair price is reading the marketing word.
The partial cash out is a more recent variant: the bookmaker offers to settle half the stake at the cash-out price and let the other half ride. The partial cash out is a price for the punter who wants to lock in some profit but keep some exposure, and the price is set on the same logic as the full cash-out. The punter who uses partial cash out as a hedging tool is paying the bookmaker’s hedging premium on both sides of the split.
A live stream of a futsal match is offered by some operators, usually gated by a stake on the event or by an active account balance. The stream is not a betting input: it is a viewing input, and the punter who bets on a stream they have not paid for is reading the marketing word. The stream gives the punter information the bookmaker has already priced; the value is in the punter’s reading of that information, not in the stream itself.
How a tip is built, and what it costs the punter who builds one
A tip is built from inputs, not from inspiration. The inputs are: the line-ups, with the named players and the named absences; the form, with the last five results and the goals scored and conceded; the head-to-head, with the record between these two sides; the venue, with the home record of the home side and the away record of the away side; and the price, with the bookmaker’s price on each outcome and the implied probability of each outcome after the margin has been taken out.
The line-ups are the input that the trade over-uses. A starting goalkeeper named on the team sheet is information the trade prices into the pre-match market within minutes of the team sheet being published, and a punter who reads the team sheet at kick-off and bets on it has read information the bookmaker has already priced. The line-ups that move a price are the line-ups published late — the late changes, the injury-time call-ups, the starting five that does not match the announced one. The punter who has a feed of late team-sheet news is paying for an edge; the punter who has only the pre-match team sheet is paying nothing.
The form is the input that the trade over-relies on. The last five results of a futsal side are a small sample, and a side that has won four and lost one is not, on form, a 4/1 shot. The trade’s “form” word carries a heavier meaning than the numbers behind it; the punter who treats form as a probability is over-weighting the recent past. The number of matches in the recent past that matter is the number of matches in the same competition, at the same venue, against comparable opposition. Anything else is a sample too small to price.
The head-to-head is the input that the trade under-uses. A futsal side that has won the last six meetings against the same opposition is not, on the head-to-head, a 1.20 shot. The trade’s “head-to-head” word carries a heavier meaning than the numbers behind it; the punter who treats head-to-head as a probability is over-weighting the recent past between these two specific sides. The head-to-head is one input among many, and the punter who bets on it alone is betting on a small sample.
The price is the input that the trade under-prices. A futsal side priced at 1.50 has an implied probability of 66.7 %, not 50 %, and the margin inside the price takes the implied probability higher. A punter who estimates the side’s chance of winning at 70 % and the bookmaker’s price at 1.50 is looking at a price that does not offer value: the punter’s probability is 70 %, the implied probability is 66.7 %, and the difference is in the bookmaker’s favour once the margin is taken out. A punter who estimates the side’s chance of winning at 75 % has a value bet: the price offers 66.7 % of implied probability and the punter believes the probability is 75 %. The arithmetic of value is the arithmetic of the difference.
Staking is an input often over-emphasised. A punter who stakes 10 % of their bank on a single bet risks losing half their capital after five consecutive losses; a punter who stakes 1 % risks only 5 %. The bankroll is the punter’s working capital, and the unit stake is the fraction of the bank the punter is willing to lose on a single bet. The punter who stakes a fixed unit, regardless of how confident they are in the bet, is using the unit-staking method; the punter who stakes a variable unit, in proportion to the perceived edge, is using the Kelly method or a fractional Kelly. The Kelly method maximises the bankroll’s expected growth but produces wild swings; the fractional Kelly reduces the swing at the cost of growth. The punter who stakes more on a “sure” bet is over-staking; no bet is sure.
The bankroll discipline is the input that the trade under-uses. A punter who chases losses is staking on emotion; a punter who raises the unit stake after a winning run is staking on emotion; a punter who places a bet to “get back to even” is staking on emotion. The bankroll discipline is the one input the punter controls in full: the punter decides the unit stake, the punter decides the number of bets per day, the punter decides when to stop. The trade’s word “tilt” describes the punter who has stopped deciding.
The software that the trade uses — the stats packages, the odds comparison sites, the model-driven pricing tools — is a real input, and the punter who builds a model from public data and tests it on historical matches is doing the work of a professional. The model that has not been tested is a hypothesis; the model that has been tested on out-of-sample data is a tool. The punter who treats a model as a tool has accepted that the model’s edge is small, that the model’s edge will decay as the market responds, and that the model’s edge has to be re-tested as the market changes.
Markets, odds and how a futsal bet is settled
Futsal is priced by GB bookmakers under three market families. The match-result market (1X2) is a three-outcome market: home win, side draw, away win. The draw in futsal is a frequent outcome, more frequent than in outdoor football at the same level, because the game is shorter and the goalkeeper has fewer save requirements. The bookmaker’s margin on a three-outcome market is wider than the margin on a two-outcome market, because the third outcome carries its own probability slice. The punter who reads a 1X2 market as if it were a two-outcome market is under-counting the draw.
The totals market on futsal is the over/under on the number of goals. The totals market in futsal is structured around the size of the court (40 m by 20 m), the number of substitutions (up to nine, unlimited), the ball’s lower bounce (size four), and the rule from the sixth accumulated foul. A line of over 5.5 goals is ordinary on a competitive match; a line of over 7.5 goals is generous. The punter who reads a futsal totals line as if it were a football totals line is over-counting the expected goals.
The handicap market on futsal is the Asian or European handicap, applied to the match result. A handicap of -1 on the home side means the home side has to win by two clear goals for the bet to land. The handicap market in futsal carries a wider margin than the 1X2 market, because the handicap is a derivative of the 1X2 and the bookmaker adds a margin on the derivative. The punter who reads a futsa handicap as if it were a football handicap is over-counting the expected margin.
The bet builder is a same-game multi: a bet that combines several selections from a single match — the home win, the over 4.5 goals, the home side to score first — into one price. The bet builder’s combined price is the multiplication of the individual prices, and the bet builder’s margin is the multiplication of the individual margins. The bet builder at three legs has a margin roughly three times the single-leg margin. The punter who reads a bet builder as a single bet is under-counting the margin.
The accumulator (the trade’s “acca”) is a multi-leg bet across several matches. The acca’s combined price is the multiplication of the leg prices, and the acca’s margin is the multiplication of the leg margins. The acca at four legs has a margin roughly four times the single-leg margin; the acca at eight legs has a margin roughly eight times the single-leg margin. The punter who reads an acca as a single bet is under-counting the margin, and the acca insurance — the trade’s offer to refund the stake as a free bet if one leg loses — does not reduce the margin on the winning legs.
The each-way bet is two bets of equal stakes: a win bet and a place bet. The place terms are the bookmaker’s own, and the place terms vary by sport, by event and by the number of runners. The each-way stake is twice the unit stake, because the punter is placing two bets. The each-way payout is the win payout if the selection wins, the place payout if the selection places, and zero if the selection is unplaced. The each-way bet on a futsal event is rarer than the each-way bet on a horse race, and the punter who reads an each-way market as if it were a horse racing market is over-counting the place terms.
The starting price (SP) is the price the bookmaker records at the off; the best odds guaranteed (BOG) is the offer to pay the bigger of the SP or the price the punter took. BOG is standard on UK and Irish horse racing at most GB bookmakers, and is offered on some other sports on selected events. The punter who bets without BOG and takes a short price pre-race is taking a price that may move against them; the punter who bets with BOG is protected against the price moving up, but not against the price moving down.
The non-runner rule and the Rule 4 deduction are bookmaker rules that govern what happens when a selection is withdrawn. The Rule 4 deduction reduces the price of the remaining selections by a table of percentages set by the trade. The deduction is the bookmaker’s adjustment for the changed market; it is not the punter’s loss, but it is the punter’s reduced return.
The sport, its tournaments and the prices a futsal punter sees
Futsal originated in 1930 in Montevideo, Uruguay, created by Juan Carlos Ceriani for YMCAs. FIFA is the highest governing body. The first FIFA-organised futsal World Cup was held in 1989, and the inaugural FIFA Futsal Women’s World Cup took place in the Philippines in 2025. The tournament calendar the trade prices runs around the FIFA Futsal World Cup, the continental futsal championships (UEFA Futsal Championship, CONMEBOL Copa América de Futsal, AFC Futsal Asian Cup), the FIFA Futsal World Cup qualifiers, the national leagues (the Spanish LNFS, the Portuguese Liga Placardus Sports, the Brazilian Liga Nacional de Futsal, the Russian Superliga, the Japanese F.League), and the club competitions (the UEFA Futsal Champions League).
The market depth varies sharply by tournament. The UEFA Futsal Champions League and the Spanish LNFS carry the deepest bookmaker coverage; the smaller national leagues carry thinner coverage with wider margins. The punter who bets on a deep market is paying a tighter margin; the punter who bets on a thin market is paying a wider margin for the same reason — the bookmaker has less competition and a less liquid book. The price the bookmaker offers is a function of the bookmaker’s risk on that market, and the bookmaker’s risk on a thin market is the bookmaker’s own position.
The bookmaker’s own catalogue on a futsal event is structured around the pre-match 1X2, the totals, the handicap, the bet builder, and a small set of player markets (first goalscorer, anytime goalscorer, total player goals). The in-play catalogue is a subset of the pre-match catalogue, with the live prices moving as the game progresses. The cash-out catalogue is the full catalogue of unsettled bets on the event. The punter who reads the pre-match catalogue as the complete catalogue is missing the live catalogue, and the punter who reads the live catalogue as the complete catalogue is missing the cash-out catalogue.
The data that the punter uses to build a tip is, on a deep market, public: the team sheets, the recent form, the head-to-head, the venue. On a thin market the data is patchy: the team sheets may not be published in English, the recent form may be from a different competition format, the head-to-head may be a single meeting years ago. The punter who bets on a deep market has the data; the punter who bets on a thin market has the data they can find, and the price they take is the price that reflects the bookmaker’s view of the data the bookmaker has.
The trading volume on a futsal event is a fraction of the trading volume on a football event, and the fraction is the reason the margin is wider. The bookmaker’s cost of carrying a position on a thin market is higher than the bookmaker’s cost on a deep market; the punter’s cost of betting on a thin market is higher than the punter’s cost on a deep market. The trade’s “liquidity” word describes the trading volume; the punter’s “margin” word describes what they pay.
The featured bookmakers, ranked by what the comparison found
The list below is not a recommendation and not a ranking; it is the set of bookmakers the Gambling Commission’s public register of remote operating licences shows as licensed for fixed-odds sports betting in Great Britain, with a futsal line on the site or app. The punter who chooses between them chooses on the basis of the futsal catalogue depth, the in-play catalogue depth, the live-streaming catalogue, the bet builder catalogue, the payment methods, and the bonus terms. Every brand below has been checked against the register on the date shown under the page headline.
| Brand | Gambling Commission licence | What the operator’s own terms state |
|---|---|---|
| BetTom | 64959 (Bet Tom Limited) | Sports welcome offer of 50% back as a free bet of up to £50, with a matching 50% back up to £50 as free slot funds for casino play |
| VBet | 44662 (SCGO Limited) | Bet Builder, pre-match and in-play betting, live streaming and a live calendar with results and stats |
| DAZN Bet | 48756 (DZBT Limited) | Deposits start at £5 by debit card, Apple Pay, Paysafecard, Trustly and Skrill, and at £20 by PayPal, with no processing fees |
| Betfred | 39544 (Petfre (Gibraltar) Limited) | Bet Builder, Sub Switch, Racing Post data, Extra Places, live casino and bingo |
| DragonBet | 64908 (DragonBet Ltd) | Cash out both in-play and pre-match, and live streaming of racing |
| Fafabet | 57385 (Taichi Tech Limited) | Best Odds Guaranteed on UK and Irish horse racing win and each-way bets from 9am on race days, paying the bigger of the SP or the taken price |
| London Bet | 66162 (Thistle Bet Limited) | Sports betting on football, tennis, horse racing, greyhounds, darts, golf, cricket, NFL, NBA, MLB, snooker, with Pragmatic Play casino slots and live in-play betting |
| Octobet | 62545 (Octopus Game Limited) | Best Odds Guaranteed on UK and Irish horse racing, up to £150 per customer per race |
| Geoff Banks | 54095 (GB Sports Advisors Limited) | Live in-play prices and ante-post prices on future events |
| LiveScore Bet | 56859 (LiveScore Betting and Gaming (Gibraltar) Limited) | Debit cards (Visa and Mastercard), Apple Pay, PayPal, Pay by Bank (Open Banking) and Revolut Pay |
The licence figures are the Commission’s remote operating licence numbers against the running account. Every brand runs under a remote general betting standard (real events) category; none of them is the “only” licensed brand, and the listing is not a ranking. The “what the operator’s own terms state” column is what the operator’s own materials say about the named feature, not what the operator promises to do, and the punter who reads the column as a guarantee is reading the marketing word.
BetTom
BetTom operates under Gambling Commission account 64959, licensed to Bet Tom Limited. The brand’s sports welcome offer, as described on the app, is 50% back as a free bet of up to £50 paired with 50% back up to £50 as free slot funds for casino play. The offer is a mixed-product promotion under the Commission’s published rule: an offer that requires gambling on two product types. Mixed-product promotions are banned at licensed GB sites since 19 January 2026, and a punter should check the brand’s current terms before staking to ensure compliance with the Commission’s promotion rules. Futsal enthusiasts seeking deep markets might find BetTom’s offering limited and could benefit from exploring bookmakers with broader catalogues.
VBet
VBet operates under Gambling Commission account 44662, licensed to SCGO Limited. The platform features Bet Builder, pre-match and in-play betting, live streaming and a live calendar with results and stats. Futsal punters wanting same-game multi markets or live streams on selected events will find these tools available. The live calendar serves as a scheduling aid for those planning their week around specific in-play events. The brand is listed on the Commission’s register under the standard remote general betting category.
DAZN Bet
DAZN Bet operates under Gambling Commission account 48756, licensed to DZBT Limited. Help pages describe deposits starting at £5 by debit card, Apple Pay, Paysafecard, Trustly and Skrill, and at £20 by PayPal, with no processing fees. A futsal punter who bets small has a £5 entry point; a punter who uses PayPal has a £20 entry point. The payment-method mix is broad enough to cover most British debit cards, and the absence of credit cards is the Commission’s rule. The brand’s futsal catalogue is priced according to DAZN’s own risk; those seeking guaranteed market depth are advised to verify the current schedule before committing funds.
Betfred
Betfred operates under Gambling Commission account 39544, licensed to Petfre (Gibraltar) Limited. App descriptions name Bet Builder, Sub Switch, Racing Post data, Extra Places, live casino and bingo. Sub Switch allows for a selection switch on horse racing; Extra Places is a racing-specific enhanced each-way offer; Racing Post data provides form analysis. Futsal bettors are primarily engaging with the sportsbook rather than the racing-specific features. As a larger fixed-odds operator, Betfred typically offers deeper market coverage. Those interested in same-game multis will find the necessary tools integrated into the platform.
DragonBet
DragonBet operates under Gambling Commission account 64908, licensed to DragonBet Ltd. App descriptions name cash out for both in-play and pre-match markets, though live streaming is specific to racing. Futsal punters can use cash-out features across the available futsal catalogue. Those specifically looking for futsal live streaming should note it is not currently supported on this platform.
Fafabet
Fafabet operates under Gambling Commission account 57385, licensed to Taichi Tech Limited. The platform notes Best Odds Guaranteed (BOG) for UK and Irish horse racing win and each-way bets from 9am on race days, paying the greater of the SP or the taken price. Since BOG is specific to horse racing, futsal punters betting at Fafabet will be using the standard sportsbook without this racing-specific enhancement.
London Bet
London Bet operates under Gambling Commission account 66162, licensed to Thistle Bet Limited. While the app features sports including football, tennis, horse racing, greyhounds, darts, golf, cricket, NFL, NBA, MLB and snooker, futsal is not specifically mentioned; punters interested in futsal should verify availability directly through the sportsbook. The brand’s app carries a 17+ App Store rating, aligning with the Commission’s 18+ requirement.
Octobet
Octobet runs under Gambling Commission account 62545, with Octopus Game Limited as the licence holder. The brand’s own app description names Best Odds Guaranteed on UK and Irish horse racing, up to £150 per customer per race. BOG is a horse-racing feature, not a futsal feature, and the cap on the BOG payout is a racing-only cap.
Geoff Banks
Geoff Banks runs under Gambling Commission account 54095, with GB Sports Advisors Limited as the licence holder. The brand’s own app description names live in-play prices and ante-post prices on future events. A futsal punter at Geoff Banks has in-play and ante-post on the brand’s catalogue, and the punter who wants to take a price on a futsal tournament winner (the equivalent of an outright) has the tool.
LiveScore Bet
LiveScore Bet runs under Gambling Commission account 56859, with LiveScore Betting and Gaming (Gibraltar) Limited as the licence holder. The brand’s own help pages describe debit cards (Visa and Mastercard), Apple Pay, PayPal, Pay by Bank (Open Banking) and Revolut Pay. The payment-method mix is broad enough to cover most British debit cards and e-wallets, with the absence of credit cards being the Commission’s rule rather than the brand’s choice. The brand’s futsal catalogue is the line LiveScore Bet has priced under its own risk.
The arithmetic of a margin on a futsal market
Understanding the bookmaker’s margin is the key to reading any market, and the simplest calculation is the one a punter can do on the betting slip. Take an illustrative two-way market priced 1.90 / 1.90 — a price used here as an example, not as a live quote from a sportsbook. The implied probability of each side, before the margin, is 1 ÷ 1.90 = 52.6 %, and the sum of the two implied probabilities is 105.3 %. The 5.3 percentage points above 100 % are the book’s take on every unit staked, and the punter’s “payout share” on a winning selection is 1 ÷ 105.3 % = 94.7 % of stake.
The margin is 1 minus the payout share, which is 5.3 % in this example. The punter who stakes £100 on this market at this price, on a market where every selection is equally likely, gets back £94.70 across both outcomes in expectation. The £5.30 difference is the book’s edge. The punter who has no information edge over the market loses £5.30 of every £100 staked, before the wagering requirement on a bonus is taken into account.
The same arithmetic on a tighter 1.95 / 1.95 market gives a payout share of 97.4 % and a margin of 2.6 % — half the cost of the 1.90 / 1.90 example. The same arithmetic on a wider 1.85 / 1.85 market gives a payout share of 92.0 % and a margin of 8.0 %. The price the punter sees is the price the punter pays, in the sense that the punter’s expected return on a market at price X is 1 minus the margin. The punter who learns to read the implied probability of each side — and to add them to find the margin — has learned the second most useful thing the trade teaches.
The punter who applies the same arithmetic to a three-way market (1X2 on a futsal match) gets a wider margin because the third outcome takes its slice. A 2.20 / 3.40 / 2.80 line, the kind a bookmaker might print on a competitive futsal match, sums to 45.5 % + 29.4 % + 35.7 % = 110.6 % implied; the overround is 10.6 %, implying a margin of 9.6 % — roughly twice the two-way margin in the example above. The punter who reads a 1X2 market as if it were a two-way market is under-counting the margin by the third outcome’s slice.
A band of multiples of, for an accumulator, the trade’s “acca”, the leg prices multiply into one combined price, and the leg margins multiply into a combined margin that is wider than any single leg’s margin. A four-fold of legs at 2.00 / 1.80 / 1.95 / 2.10 produces a combined price of 14.65, an implied probability of 6.83 %, and a payout share of 6.83 % × (sum of leg implieds) = 6.83 % × (1/2.00 + 1/1.80 + 1/1.95 + 1/2.10) = 6.83 % × 1.97 = 13.5 % implied across the 41.7 % implied on the four legs taken alone. The acca punter is paying 28.2 percentage points of margin, in expectation, across the four legs. The punter who reads an acca as a single bet is reading the marketing word and not the margin.
Frequently asked questions
How does a punter bet on a futsal league?
A licensed GB bookmaker’s sportsbook lists the futsal leagues it prices — the Spanish LNFS, the Portuguese Liga Placardus Sports, the Brazilian Liga Nacional de Futsal, the Russian Superliga, the Japanese F.League, the UEFA Futsal Champions League and the international tournaments. The punter opens an account, completes the Commission’s identity check (name, address, date of birth), deposits by debit card or bank-based payment, opens the futsal tab, selects the match, selects the market (1X2, totals, handicap, bet builder), enters the stake on the slip, and confirms the bet. Settled bets pay the stake multiplied by the decimal odds if the selection wins.
What is a value bet, and why is no tip ever certain?
A value bet is a price the punter’s own probability estimate exceeds, after the bookmaker’s margin has been taken out. The estimate has to come from inputs the punter can defend — line-ups, form, head-to-head, venue, the bookmaker’s own price. No tip is certain because the bookmaker’s margin sits inside every price, and the margin collects its share over hundreds of bets whether the punter wins or loses. A punter who bets only on prices the estimate exceeds is the punter who pays the margin the fewest times.
What is the bookmaker’s margin, and how is it seen in the odds?
The bookmaker’s margin is the slice of every market the bookmaker keeps, expressed as a percentage of the total stake. On a two-way market priced 1.90 / 1.90, each side implies 52.6 % probability, the sum is 105.3 %, and the 5.3 % above 100 % is the margin. The closer the sum is to 100 %, the fairer the market; the further from 100 %, the wider the margin. The punter who adds the implied probabilities before staking is reading the margin in the odds.
How is the return on a bet worked out from the stake and the odds?
The return on a winning bet is the stake multiplied by the decimal odds. A £10 stake at 2.50 returns £25; a £10 stake at 1.50 returns £15. The net profit is the return minus the stake — £15 on the 2.50 stake, £5 on the 1.50 stake. For an accumulator the leg odds multiply into one combined price, and the same arithmetic applies to the combined price. The punter who knows the multiplication has taken the arithmetic surprise out of the bet.
How is it checked that a bookmaker holds a Gambling Commission licence?
The Commission’s public register, on the Commission’s own site, lists every licence holder with the account number and the licensed activities. The punter searches by business name, trading name, domain or account number; if the brand is on the register, the licence number, the licence holder and the licensed activities are listed; if not, the brand is unlicensed for the GB market. The punter who checks the register before staking has checked the licence. A domain that ends in .co.uk is not proof of a licence; licensed operators use .com and .co.uk interchangeably.
Which tools for controlling play does a licensed bookmaker have to offer?
A licensed remote bookmaker has to be part of GAMSTOP, must offer deposit limits on a fixed time frame, must run a financial vulnerability check at the £150 deposits-minus-withdrawals threshold over a rolling 30 days, must offer self-exclusion through the operator and through GAMSTOP, must publish safer-gambling information and links to GamCare, GambleAware, the NHS gambling clinics and Gamblers Anonymous. The punter who uses these tools is using the licence condition. The tools are not optional; they are the licence.
Football – oddsguaranteed
Content created by the «oddsguaranteed» team
